
filters
Even on well-built bars, most bars are uneventful, and a classifier trained on every one of them spends its capacity learning that nothing happened. AFML’s answer (§2.5.2) is to sample: keep only the bars at which something measurable occurred, and label those. The filter that decides which bars is the first modelling choice in the pipeline, and everything downstream — labels, sample weights, cross-validation — inherits its timestamps.
The symmetric CUSUM filter
Section titled “The symmetric CUSUM filter”CUSUM is a quality-control method (Page, 1954) for detecting that the mean of a process has shifted away from a target. Applied to returns with a target of zero, it accumulates upward and downward drift separately and floors each accumulator at zero:
where . Bar is an event when or , and
the accumulator that fired is reset to zero. This is AFML’s Snippet 2.4 with one difference:
the snippet differences whatever series it is given, and this implementation always takes
log returns of close. Pass prices, not returns.
The floor is what makes the filter useful. A price that wanders up 0.9% and back down does not trigger it and leaves no residue, whereas a Bollinger-band rule fires repeatedly while a price hovers at the band. CUSUM needs a full run of length from the last reset, in one direction net of reversals, so it fires once per move.
import mathimport randomfrom datetime import datetime, timedeltafrom statistics import median
from openquant import filters
# 600 one-minute closes. Minutes 300-399 are four times as volatile as the rest.rng = random.Random(11)start, price, close, stamps = datetime(2024, 1, 2, 9, 30), 100.0, [], []for i in range(600):    price *= math.exp(rng.gauss(0, 0.004 if 300 <= i < 400 else 0.001))    close.append(price)    stamps.append((start + timedelta(minutes=i)).strftime("%Y-%m-%d %H:%M:%S"))
h = 0.01  # fire when the cumulative log return since the last event reaches 1%events = filters.cusum_filter_indices(close, h)volatile = [i for i in events if 300 <= i < 400]print(f"{len(events)} events from {len(close)} bars; {len(volatile)} of them in the volatile 100")
gaps = [(a, b - a) for a, b in zip(events, events[1:])]print("median bars between events: "      f"calm {median(g for a, g in gaps if not 300 <= a < 400):.0f}, "      f"volatile {median(g for a, g in gaps if 300 <= a < 400):.0f}")
print("first three:", filters.cusum_filter_timestamps(close, stamps, h)[:3])
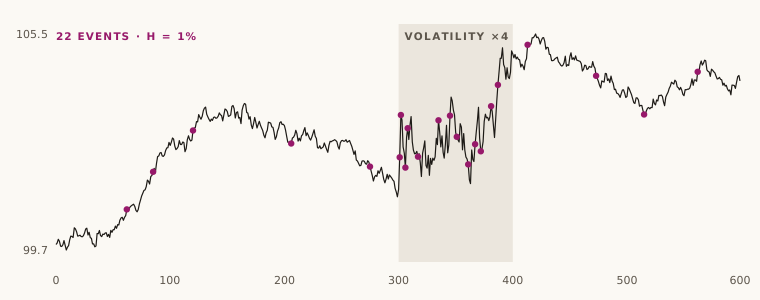
22 events from 600 bars; 13 of them in the volatile 100median bars between events: calm 44, volatile 6first three: ['2024-01-02 10:32:00', '2024-01-02 10:55:00', '2024-01-02 11:30:00']A sixth of the bars produce more than half the events, which is the behaviour you want from a sampler and also the problem with a fixed : in the volatile stretch an event arrives every six bars, and their labels will overlap heavily.
Choosing h
Section titled “Choosing h”is in log-return units and means “a move worth labelling”. Two practical anchors:
- Tie it to the label. If the triple-barrier profit target is 1.5%, an near 1.5% asks the classifier about moves of the size it is being paid to predict. An far below the barrier width mostly samples noise that never reaches a barrier.
- Tie it to volatility. A constant fires too often in turbulent regimes and rarely in
calm ones. Pass one threshold per bar instead — typically a multiple of
get_daily_vol— and bar is compared with element . In Rust that isThreshold::Dynamic; a vector shorter than the series is aFilterError::MissingDynamicThreshold, not a silent truncation. In Python, pass a list, NumPy array or pandas Series asthresholdinstead of a number.
From Python, a per-bar threshold must have exactly one value per price, or it is a
ValueError. Element 0 is never read (the first return is at bar 1), so it may be NaN, as
the first value of a volatility estimate usually is. Every other element, and a scalar
threshold, must be finite and non-negative: a NaN threshold would silently never fire and a
negative one would fire on every bar. Fill a volatility estimate’s warm-up before passing it.
import mathimport random
import numpy as npfrom openquant import filters
# The same 600 closes as above: minutes 300-399 are four times as volatile.rng = random.Random(11)price, close = 100.0, []for i in range(600):    price *= math.exp(rng.gauss(0, 0.004 if 300 <= i < 400 else 0.001))    close.append(price)
# h_t = 5 x the trailing 50-bar standard deviation of log returns; 1% until it is defined.returns = np.diff(np.log(close), prepend=np.nan)vol = np.array([returns[t - 49 : t + 1].std(ddof=1) if t >= 50 else np.nan for t in range(600)])h = np.where(np.isnan(vol), 0.01, 5.0 * vol)
events = filters.cusum_filter_indices(close, h)volatile = [i for i in events if 300 <= i < 400]print(f"{len(events)} events from {len(close)} bars; {len(volatile)} of them in the volatile 100")print("a constant array is the scalar filter:",      filters.cusum_filter_indices(close, [0.01] * 600) == filters.cusum_filter_indices(close, 0.01))
29 events from 600 bars; 6 of them in the volatile 100a constant array is the scalar filter: TrueThe threshold rises with the turbulence, so the volatile stretch yields 6 events instead of 13 and the calm stretches more: the sampler now fires on moves that are large for their regime, which is what a volatility-scaled triple barrier will then label.
Whichever you use, count the events and look at their spacing before labelling. Events closer
together than the label horizon produce overlapping labels; sampling
measures that overlap and sample-weights corrects for it, but
neither removes it.
The z-score filter
Section titled “The z-score filter”z_score_filter_indices(close, mean_window, std_window, threshold) marks bar when
with the rolling mean over mean_window bars, the rolling sample
standard deviation (ddof = 1) over std_window bars, both including bar , and the
threshold. It is not from AFML; it is ported from mlfinlab. Three properties to know before
using it:
- It is one-sided. Only upward excursions are events; a crash three deviations below the mean is not. Negate the series to sample the downside.
- It works on price levels, not returns, so on a trending series the price sits above its trailing mean and the filter fires in runs rather than once per move.
- It has no reset, so consecutive bars above the band are consecutive events.
From Rust
Section titled “From Rust”use openquant::filters::{cusum_filter_indices, FilterError, Threshold};
let close = vec![100.0, 100.4, 100.9, 101.3, 101.0, 100.2, 99.6, 99.9];
// Fixed 1% threshold: one upward event, then one downward.let events = cusum_filter_indices(&close, Threshold::Scalar(0.01))?;assert_eq!(events, vec![3, 5]);
// Per-bar thresholds must cover the series.let too_short = cusum_filter_indices(&close, Threshold::Dynamic(vec![0.01; 3]));assert!(matches!(too_short, Err(FilterError::MissingDynamicThreshold { index: 3, available: 3 })));cusum_filter_timestamps and z_score_filter_timestamps return the timestamps at the event
positions instead, and report a timestamp slice that is too short as
FilterError::TimestampIndexOutOfBounds.
What to watch for
Section titled “What to watch for”- No look-ahead, but no warm-up either. The filter uses only returns up to bar , so its events are safe to label. Its accumulators start at zero at the first bar, so the first event on a series that starts mid-move comes late; drop a burn-in stretch if that matters.
- Both accumulators can be non-zero at once. Only the side that fires is reset. After an upward event, keeps whatever downward drift it had.
- Events are bars, not trades. An event at bar is known at the close of bar .
Entering at that close is optimistic;
labelingmeasures outcomes from the event bar’s close, so any execution delay is yours to model.
Related modules
Section titled “Related modules”data-structures— the bars this filter samples from.labeling— triple-barrier labels at the sampled events.util-volatility— the volatility estimate behind a dynamic threshold.structural-breaks— CUSUM tests for a change in regime, which share the name and the statistic but answer a different question.
API reference
Section titled “API reference”Python
Section titled “Python”Signatures, parameters, return values and errors for every function: openquant.filters.
filters.cusum_filter_indices— Symmetric CUSUM filter returning event positions (AFML section 2.5.2.1, Snippet 2.4).filters.cusum_filter_timestamps— Symmetric CUSUM filter returning event timestamps (AFML section 2.5.2.1, Snippet 2.4).filters.z_score_filter_indices— Rolling z-score filter returning event positions (ported from mlfinlab; not in AFML).filters.z_score_filter_timestamps— Rolling z-score filter returning event timestamps (ported from mlfinlab; not in AFML).
Rustdoc for this commit, with every public item of openquant::filters (after a crates.io release the same pages are on docs.rs):