
synthetic_backtesting
Where to take profit and where to stop out are usually chosen by trying many pairs of levels
on history and keeping the best. With two free parameters and one price path, that is about
the easiest way there is to overfit a backtest (AFML §13.3). Chapter 13’s alternative is to
stop optimising on history at all. Estimate the process the price follows, which takes two
or three parameters and is hard to overfit; simulate many paths from it; and choose the exit
rule on those. The rule is then tuned to the character of the series, not to the accidents of
one sample. The Python module is openquant.synthetic_bt.
The procedure
Section titled “The procedure”1. Fit. calibrate_ou_params(prices) fits a discrete Ornstein–Uhlenbeck process, an
AR(1), by least squares:
sets the speed of mean reversion, with half-life : 6.6 steps at
, 138 at . is a random walk, which does not revert.
OuProcessParams carries phi, equilibrium, sigma, the regression’s r_squared, and
stationary, true when .
2. Simulate. generate_ou_paths(params, initial_price, n_paths, horizon, seed) draws the
paths. initial_price is where the trade is entered, and its distance from equilibrium is
the forecast: the whole expected profit of a long position comes from
.
3. Evaluate. evaluate_rule_on_paths enters long at the first price of every path
and exits at the first step where the profit reaches profit_taking or the loss reaches
stop_loss, or at max_holding_steps. It returns the mean, deviation and Sharpe ratio of the
exit PnL across paths, the win rate and the average holding time.
4. Search. search_optimal_trading_rule evaluates every pair on a grid — on the same
paths, so rules are compared on identical draws — and returns the surface sorted by Sharpe
ratio. run_synthetic_otr_workflow does all four steps.
A rule exists only if the process reverts
Section titled “A rule exists only if the process reverts”AFML’s central experimental result (§13.6) is negative. When the process mean-reverts, the
Sharpe surface has a clear ridge and an optimal rule can be read from it. As
approaches 1 the surface flattens, and at a random walk there is no optimum to find: whatever
pair a historical grid search returns is noise. detect_no_stable_optimum looks for that
condition and reports it in diagnostics.
import random
from openquant import synthetic_bt as sb
def history(phi, equilibrium=100.0, sigma=1.0, n=1500, seed=3):    rng, p, out = random.Random(seed), equilibrium, []    for _ in range(n):        p = (1 - phi) * equilibrium + phi * p + sigma * rng.gauss(0, 1)        out.append(p)    return out
grid = [0.5, 1.0, 2.0, 4.0, 8.0]  # barrier widths in price units; sigma is 1for label, phi in (("mean-reverting", 0.90), ("near random walk", 0.995)):    res = sb.run_synthetic_otr_workflow(        history(phi), initial_price=97.0, n_paths=4000, horizon=60, seed=11,        profit_taking_grid=grid, stop_loss_grid=grid, max_holding_steps=59,        annualization_factor=1.0)    p, best, d = res["params"], res["best_point"], res["diagnostics"]    print(label)    print(f"  fitted phi {p['phi']:.3f}, equilibrium {p['equilibrium']:.1f}, sigma {p['sigma']:.2f}")    print(f"  best rule: take profit {best['profit_taking']}, stop loss {best['stop_loss']}, "          f"Sharpe {best['sharpe']:.2f}, win rate {best['win_rate']:.0%}")    print(f"  surface: best - median {d['peak_margin']:.2f}; no stable optimum: {d['no_stable_optimum']}")
mean-reverting fitted phi 0.903, equilibrium 99.8, sigma 0.99 best rule: take profit 2.0, stop loss 8.0, Sharpe 4.95, win rate 100% surface: best - median 4.17; no stable optimum: Falsenear random walk fitted phi 0.992, equilibrium 95.9, sigma 0.99 best rule: take profit 0.5, stop loss 8.0, Sharpe 0.06, win rate 89% surface: best - median 0.08; no stable optimum: TrueBoth trades are entered at 97. In the first case the fitted equilibrium is 99.8, so the position has about three points of expected reversion in its favour and the surface shows where to collect it. In the second, 1,500 observations of a near random walk put the “equilibrium” at 95.9 — below the entry, though the data were generated around 100 — and no rule does better than a Sharpe ratio of 0.06. The search still names a best rule. The diagnostic is what tells you to ignore it.
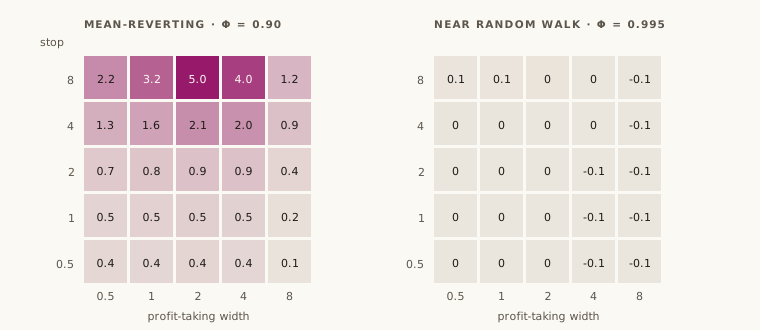
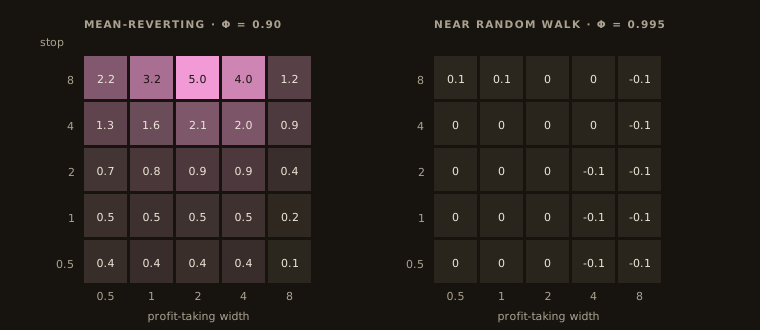
The shape on the left is the book’s: for a mean-reverting process with a favourable forecast, profit-taking belongs near the expected reversion and stop-losses hurt, because a stop-out realises a loss the process would have recovered.
From Rust
Section titled “From Rust”use openquant::synthetic_backtesting::{ calibrate_ou_params, evaluate_rule_on_paths, generate_ou_paths, OuProcessParams, TradingRule,};
// An exact AR(1) recursion with no noise term would have sigma = 0 and be refused, so// perturb it slightly: phi = 0.8 around 50.let mut prices = vec![40.0];for i in 1..400 { let wobble = if i % 2 == 0 { 0.05 } else { -0.05 }; prices.push(0.2 * 50.0 + 0.8 * prices[i - 1] + wobble);}let fitted = calibrate_ou_params(&prices)?;assert!((fitted.phi - 0.8).abs() < 0.01 && (fitted.equilibrium - 50.0).abs() < 0.01);assert!(fitted.stationary);
// Simulation is reproducible for a seed, and every path starts at the entry price.let params = OuProcessParams { phi: 0.9, intercept: 10.0, equilibrium: 100.0, sigma: 1.0, r_squared: 0.0, stationary: true };let paths = generate_ou_paths(params, 97.0, 2_000, 60, 11)?;assert_eq!(paths, generate_ou_paths(params, 97.0, 2_000, 60, 11)?);assert!(paths.iter().all(|p| p.len() == 60 && p[0] == 97.0));
// Entered three points below equilibrium, a wide stop beats a tight one.let wide = evaluate_rule_on_paths(&paths, TradingRule { profit_taking: 2.0, stop_loss: 8.0 }, 59, 1.0)?;let tight = evaluate_rule_on_paths(&paths, TradingRule { profit_taking: 2.0, stop_loss: 0.5 }, 59, 1.0)?;assert!(wide.sharpe > tight.sharpe && wide.win_rate > 0.95);generate_ou_paths simulates from intercept and phi; equilibrium is carried for
reference, so when building OuProcessParams by hand keep them consistent:
intercept = (1 − phi) × equilibrium.
What to watch for
Section titled “What to watch for”- Barriers are in price units, not multiples of volatility. AFML’s experiments set
, so its grids read as multiples of . Here a grid of
[0.5, …, 8.0]on an instrument with is all noise-width barriers. Scale the grids by the fittedsigma. - Long only. Every path is a long entry at
initial_price. For a short, negate the series and the entry. - A high Sharpe ratio here can mean a capped payoff, not a good trade. The best rule in the example wins 100% of the time because nearly every path reaches +2 before the horizon, so the PnL is almost the constant 2 and its deviation is tiny. That Sharpe ratio of 4.95 measures how reliably the simulated process reverts. Its risk is the risk that the real one does not, which is nowhere in the number.
annualization_factormultiplies by its square root and ignores holding time. A rule that exits in 3 steps and one that holds for 59 are scaled alike. Use 1.0 and read the Sharpe ratio as per trade, alongsideavg_holding_steps.- The stability thresholds are heuristics.
StabilityCriteria::default()is , margin 0.20, surface deviation 0.10, best Sharpe 0.30, andrun_synthetic_otr_workflowuses the same four when its threshold arguments are left asNone. They are this library’s numbers, not AFML’s — the book shows the flattening but sets no thresholds. Look at the surface. - The model is the assumption. Everything downstream is conditional on the price being
a stationary AR(1) with constant parameters.
r_squaredis always high for a persistent series and says nothing about that;stationaryis true for any , including 0.999. Fit on several windows and check that and the equilibrium hold still. - The forecast is an input.
initial_pricerelative toequilibriumdecides the expected profit. Entering at the equilibrium gives a surface with no edge in it however strongly the process reverts.
Related modules
Section titled “Related modules”labeling— the triple barrier these two levels feed.backtesting-engine— resampling history, the other alternative to a single walk-forward.backtest-statistics— deflate whatever rule is finally traded.structural-breaks— test whether the fitted regime is still in force.
API reference
Section titled “API reference”Python
Section titled “Python”Signatures, parameters, return values and errors for every function: openquant.synthetic_bt.
synthetic_bt.run_synthetic_otr_workflow— End-to-end optimal-trading-rule search on synthetic O-U paths.synthetic_bt.calibrate_ou_params— Fit a discrete Ornstein-Uhlenbeck (AR(1)) process to a price series.synthetic_bt.generate_ou_paths— Simulate O-U price paths from given process parameters.synthetic_bt.evaluate_rule_on_paths— Evaluate one profit-taking/stop-loss rule on every path.synthetic_bt.search_optimal_trading_rule— Search a PT/SL grid on given paths and diagnose the response surface.synthetic_bt.detect_no_stable_optimum— Flag a PT/SL response surface that lacks a stable optimum (the flattening of AFML §13.6).
Rustdoc for this commit, with every public item of openquant::synthetic_backtesting (after a crates.io release the same pages are on docs.rs):