
data_structures
A market does not produce information at a constant rate per minute. It produces it per trade, per share, per dollar. Sampling a price every five minutes therefore oversamples the quiet hours and undersamples the open, the close and every news release — and the returns of such a series are heteroskedastic, serially correlated and fat-tailed for reasons that have nothing to do with the asset (AFML §2.3.1). The alternative, going back to Mandelbrot and Taylor (1967) and Clark (1973), is to let activity be the clock: close a bar every trades, every units of volume, or every dollars exchanged.
This module builds those bars from a slice of trades. It is the first step of every workflow
on this site; filters and labeling consume its
output.
What each bar type does
Section titled “What each bar type does”| Builder | A bar closes when | AFML |
|---|---|---|
time_bars | the first trade at least interval after the bar’s first trade arrives | §2.3.1.1 |
standard_bars(…, Tick) | threshold trades have accumulated | §2.3.1.2 |
standard_bars(…, Volume) | cumulative volume reaches threshold | §2.3.1.3 |
standard_bars(…, Dollar) | cumulative price × volume reaches threshold | §2.3.1.4 |
imbalance_bars | the absolute signed imbalance reaches threshold | §2.3.2.1–2, simplified |
run_bars | threshold consecutive trades move the same way | §2.3.2.3, simplified |
Three behaviours are common to all of them. The trade that crosses the threshold belongs to
the bar it closes, so bars overshoot the threshold rather than undershoot it. A trailing
partial bar is dropped — except by time_bars, which emits whatever is left as a final,
shorter bar. And time bars are anchored to the first trade of each bar, not to the wall
clock: a five-minute bar that opens at 09:30:04 closes on the first trade at or after
09:35:04.
For a dollar bar the closing condition is
with the first trade after the previous bar closed. AFML prefers dollar bars to tick and volume bars for a practical reason: a stock that doubles in price halves the number of shares a given dollar amount buys, and corporate actions change share counts outright, so only the dollar value exchanged is comparable across years (§2.3.1.4).
The information-driven bars are simplified
Section titled “The information-driven bars are simplified”imbalance_bars and run_bars are not the adaptive bars of §2.3.2. In the book the
threshold is an expectation that is re-estimated as bars form — the expected imbalance
, updated by exponentially weighted averages of previous
bars. Here threshold is a constant you supply. imbalance_bars accumulates the tick-rule
sign (weighted by nothing, volume or dollar value) and closes a bar when
reaches it; run_bars closes a bar after threshold consecutive
same-direction trades, which is a simpler condition than AFML’s count of the dominant side
within the bar. Use them as fixed-threshold variants, and do not cite them as the book’s
bars.
The point, on data
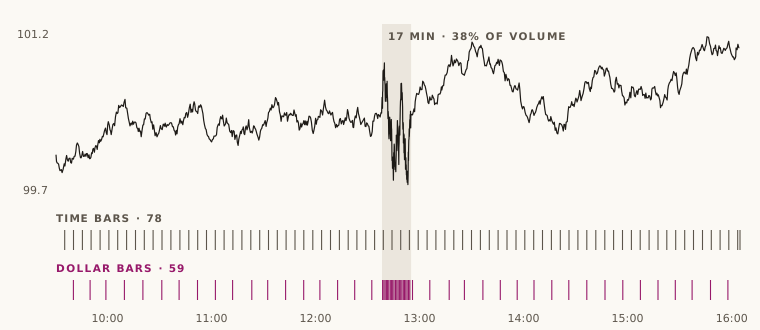
Section titled “The point, on data”The example builds one synthetic session in which seventeen minutes carry far more trading than the rest, then counts how many bars of each kind close inside those minutes.
import mathimport randomfrom datetime import datetime, timedelta
import polars as plfrom openquant import bars
# One synthetic session of 6,000 trades. Trades 2,500-3,499 are a burst:# one per second instead of one every 2-7, three times the size, more volatile.rng = random.Random(7)t, price, rows = datetime(2024, 1, 2, 9, 30), 100.0, []for i in range(6000):    burst = 2500 <= i < 3500    t += timedelta(seconds=1 if burst else rng.randint(2, 7))    price *= math.exp(rng.gauss(0, 0.0004 if burst else 0.00015))    rows.append((t, "ES", price, float(rng.randint(1, 8) * (3 if burst else 1))))burst_start, burst_end = rows[2500][0], rows[3500][0]
trades = pl.DataFrame(rows, schema=["ts", "symbol", "price", "volume"], orient="row")# The builders take OHLCV rows; a trade is a row whose four prices are equal.ohlcv = trades.select(    "ts", "symbol", open="price", high="price", low="price", close="price", volume="volume")
in_burst = trades.filter(pl.col("ts").is_between(burst_start, burst_end, closed="left"))minutes = (burst_end - burst_start).total_seconds() / 60session = (rows[-1][0] - rows[0][0]).total_seconds() / 60print(f"burst: {minutes:.0f} of {session:.0f} minutes ({minutes / session:.0%}), "      f"{in_burst.height / trades.height:.0%} of trades, "      f"{in_burst['volume'].sum() / trades['volume'].sum():.0%} of volume")
for name, frame in [    ("time 5m", bars.build_time_bars(ohlcv, interval="5m")),    ("tick 75", bars.build_tick_bars(ohlcv, ticks_per_bar=75)),    ("volume 600", bars.build_volume_bars(ohlcv, volume_per_bar=600.0)),    ("dollar 60k", bars.build_dollar_bars(ohlcv, dollar_value_per_bar=60_000.0)),]:    closes = frame.filter(pl.col("ts").is_between(burst_start, burst_end, closed="right"))    share = closes.height / frame.height    print(f"{name:11s} {frame.height:3d} bars, {closes.height:2d} close inside the burst ({share:.0%})")
burst: 17 of 394 minutes (4%), 17% of trades, 38% of volumetime 5m 78 bars, 4 close inside the burst (5%)tick 75 80 bars, 13 close inside the burst (16%)volume 600 59 bars, 22 close inside the burst (37%)dollar 60k 59 bars, 22 close inside the burst (37%)Each bar type spends its observations in proportion to its own clock. Time bars give the burst 5% of their bars because it is 4% of the session; tick bars give it 16% because it holds 17% of the trades; volume and dollar bars give it 37% because it holds 38% of the volume. A model trained on the time bars sees four observations of the only interesting quarter-hour of the day.
Choosing a threshold
Section titled “Choosing a threshold”The threshold sets how many bars you get, and that is a modelling decision, not a default to
accept. A common starting point is the number of bars you would have had with time bars:
divide the session’s total dollar volume by that count. The example traded about 3.6 million
dollars, so a threshold of 60,000 gives roughly the sixty bars that five-minute sampling gives
in a quieter session. The Python defaults (ticks_per_bar=50, volume_per_bar=100_000,
dollar_value_per_bar=5_000_000) suit no instrument in particular. Pick a number, then check
the bar count and bars.bar_diagnostics before trusting what is built on top.
Because thresholds are in absolute units, a dollar threshold fixed in 2015 produces several times as many bars on the same instrument in 2024. Over long histories, re-derive the threshold per period or scale it by a rolling average of daily dollar volume.
From Rust
Section titled “From Rust”use chrono::{Duration, NaiveDate};use openquant::data_structures::{standard_bars, time_bars, StandardBarType, Trade};
let open = NaiveDate::from_ymd_opt(2024, 1, 2).unwrap().and_hms_opt(9, 30, 0).unwrap();let trades: Vec<Trade> = (0..1_000) .map(|i| Trade { timestamp: open + Duration::seconds(i * 3), price: 100.0 + (i as f64 * 0.01).sin(), volume: 1.0 + (i % 5) as f64, }) .collect();
let dollar = standard_bars(&trades, 25_000.0, StandardBarType::Dollar)?;let five_minute = time_bars(&trades, Duration::minutes(5))?;
// Every bar carries OHLC, volume, dollar value, tick count and both of its timestamps.let first = &dollar[0];assert!(first.dollar_value >= 25_000.0);assert!(first.start_timestamp <= first.timestamp);// 1,000 trades three seconds apart: nine full five-minute bars and the partial one left over.assert_eq!(five_minute.len(), 10);A non-positive threshold or interval is an InputError, not a panic. An empty slice of
trades is valid and yields no bars.
What to watch for
Section titled “What to watch for”- Identical timestamps collapse in Python. Sub-second stamps are kept (microseconds
through
openquant.bars, which is the resolution of a Pythondatetime). But the Python builders first pass the frame throughdata.clean_ohlcv, which removes rows that repeat a(symbol, ts)pair, so two trades with exactly the same stamp collapse into one. If your feed stamps several trades identically, build bars in Rust. - The Python builders take OHLCV rows, not trades. They read
closeas the trade price andvolumeas the trade size. Feeding them one-minute OHLCV bars works and is sometimes what you want, but the result is a bar of bars: its high and low come from minute closes, not from the minute highs and lows. - Run and imbalance bars have no Python wrapper.
openquant._core.barsexposesbuild_run_barsandbuild_imbalance_bars;openquant.barsdoes not wrap them in a frame. - Bars overshoot. One block trade can be many thresholds wide, and it still closes exactly
one bar.
dollar_valueon the bar records what was actually accumulated.
Related modules
Section titled “Related modules”filters— sample events from the bars built here.labeling— label those events.microstructural-features— per-bar liquidity and order-flow features from the same trades.data— load and clean the OHLCV frame the Python builders expect.
API reference
Section titled “API reference”Python
Section titled “Python”Signatures, parameters, return values and errors for every function: openquant.bars.
bars.build_time_bars— Resample an OHLCV frame into time bars per symbol (AFML section 2.3.1.1).bars.build_tick_bars— Group an OHLCV frame into tick bars of a fixed row count per symbol (AFML 2.3.1.2).bars.build_volume_bars— Group an OHLCV frame into volume bars per symbol (AFML section 2.3.1.3).bars.build_dollar_bars— Group an OHLCV frame into dollar bars per symbol (AFML section 2.3.1.4).bars.bar_diagnostics— Summarize the statistical properties of a bar series' close-to-close returns.
Rustdoc for this commit, with every public item of openquant::data_structures (after a crates.io release the same pages are on docs.rs):